




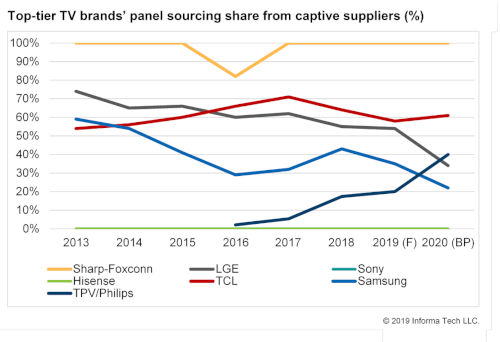
Korean LCD TV panel manufacturers will undergo restructuring and factory closures in 2020. This event is likely to trigger supply chain changes that will prompt TV manufacturers to seek alternative supply bases that are reliable and competitive enough to ensure they meet their 2020 sales targets, as reported by TV Display & OEM Intelligence Service.
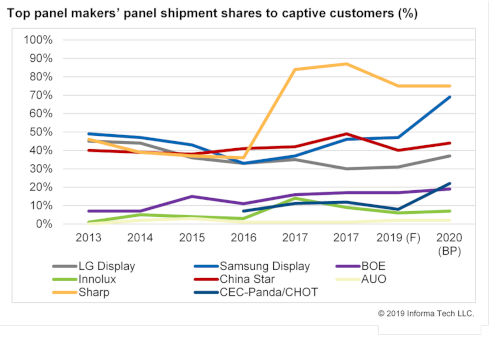 “With only a limited number of panel supply options available, TV manufacturers are turning to Chinese companies to meet their display needs,” says Deborah Yang, head of the display supply chain at IHS Markit | Technology. “Intense competition among leading Chinese suppliers and the arrival of new players is resulting in a sharp increase in the availability of panels from China.”.
The world's top three TV brands will increase their purchases from Chinese suppliers to 62.6 million screens in 2020, a 35 percent increase from 2019.
Emerging Chinese Companies as Global Suppliers of LCD TV Panels:
Competition between leading Chinese suppliers BOE Technology and China Star Optoelectronics Technology is intensifying, particularly in the supply of LCD panels from Gen 10.5 factories. Meanwhile, supply availability is improving from emerging Chinese panel manufacturers such as HKC, Nanjing CEC-Panda LCD Technology, and Xianyang Caihong Optoelectronics Technology (CHOT).
These developments will help boost sales for global TV brands such as Samsung, LG Electronics, and several Chinese companies.
Although panel supply still exceeds demand, top-tier TV brands are signing long-term supply agreements with both captive and selective external panel suppliers to ensure they secure top-priority business in 2020. Current supply dynamics and competitive shifts have led brands to rethink their purchasing plans for this year and beyond.
Getting in Shape:
Internal support, on both the supply and demand sides, is becoming critical. As such, it is important for LCD panel suppliers and TV manufacturers to form a fully integrated TV business model (FIT) together.
Strong supply momentum from panel manufacturers and strong demand from TV brands combined can optimize supply chain efficiency and boost profitability.
However, if the supply chain node weakens, it could be a burden for participants. Most major TV manufacturers have diversified panel sources and aim to gain greater sourcing power to improve their own competitiveness. However, they are not necessarily obligated to consume excess panel supplies from captive suppliers.
"When the market is dominated by a few powerful players, TV manufacturers and panel manufacturers can face several dilemmas and risks as they try to retain bargaining power," Yang noted.
In 2020, Samsung's panel supply from its captive supplier, Samsung Display, will be further reduced. Samsung Display plans to convert its LCD TV panel capabilities to quantum dot displays. Furthermore, the availability of Samsung Display's LCD TV panels will be limited from this year onward, significantly reducing its panel supply to external customers, especially Chinese TV manufacturers.
LG Electronics' sourcing volumes from LG Display will also decrease in 2020. However, LG is likely to purchase from external suppliers such as BOE Technology, HKC, and Nanjing CEC-Panda LCD Technology to compensate for the potential loss of LCD TV panel availability from LG Display in 2020.







