




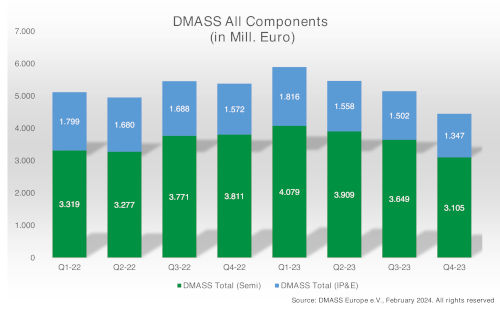
Semiconductors fell to €3.1 billion (-18.5%), while IP&E components (interconnect, passive, and electromechanical) declined by 14.3% to €1.35 billion. For the full year 2023, DMASS reported consolidated sales of €21 billion (+0.2%), narrowly surpassing the previous record set in 2022. All of the 2023 growth came from semiconductors (+4%), while IP&E declined by 7.7%.

Hermann Reiter, Chairman of DMASS: “The expected slowdown was mitigated by a very strong first half of 2023, resulting in another record year. It is true that distribution revenues were boosted by orders and sales brought forward from 2024, significantly inflating the 2023 results. As a consequence, we are now facing a market contraction that is bringing the business back in line with long-term growth averages. Our hope for 2024 lies in a general market improvement driven by the buzz surrounding artificial intelligence, which could provide a boost to the entire market. For Europe in general, and component distribution and its customers in particular, this effect will occur, at best, towards the end of 2024. The focus for distributors now must be on helping our customers develop new markets and accelerate innovation opportunities. Electronics will continue to be the driving force behind economic and social transformation.”
Semiconductors (Q4):
Semiconductor distribution sales in Europe fell 18.5% to €3.1 billion. Regionally, no country remained positive, with significant differences between regions.
In terms of products, the only major group to surprise with significant growth was microprocessors (+17.6%). All other groups declined by single digits to over 40%.

Interconnection, Passive, and Electromechanical Components (Q4):
In IP&E, the slowdown continued in the fourth quarter. The IP&E distribution market declined by 14.3% to €1,350 million in the fourth quarter. The slowdown across all three product groups remained in the lower double digits. At the national and regional levels, the quarterly performance was uneven: only two countries remained positive (Turkey and Romania), while all others experienced declines of between 5% and 25%. Year-on-year, the regional situation is almost the same; at the product level, Passives suffered more than the other two product groups (see tables).

President Hermann Reiter concludes: “However clear the downward trend may now be, and however much this has been visible and expected for quite some time, we must be cautious with predictions. Why? The challenges and opportunities in this market have become less legible than in the past, and the current dynamics are influenced by political and technological factors that are inherently disruptive, possibly in both directions. Despite this unpredictability, we are convinced that distribution will remain the stabilizing and balancing force of the market.”







