





Hermann Reiter, President of DMASS: “We have seen similar or higher growth rates in distribution in the past, but the sales levels we achieved in 2021 are unprecedented. Given the ongoing pressure in the component market—represented by extremely high backlogs, huge delays, and lead times extending well into 2023—our optimism for the new year is tempered by some concern about the effects of shortages on our customers’ growth rates. While the growth opportunities are enormous, so are the accumulated risks, such as order duplication and potential new ones, such as COVID-related supply chain disruptions and geopolitical conflicts.”
Semiconductors:
Once again, different regions and countries in Europe experienced a huge dispersion in semiconductor growth rates in the fourth quarter, ranging from 16% to 55%. However, the major countries ended up in the same range: Germany grew 44.4% to €707 million, Eastern Europe 30.5% to €467 million, Italy a surprising 50.9% to €233 million, France 43% to €170 million, and the UK 42.8% to €174 million. Year-on-year, almost all countries saw healthy double-digit growth.
By product and product group, memory was the fastest-growing semiconductor product group in the fourth quarter, increasing 64.3% to €284 million, followed by discrete products, which grew 54.9% to €155 million. The leading product groups, Analog and MOS Micro, grew 39.3% and 34.5%, respectively, to €729 million and €517 million. Power, Sensors, and Standard Logic remained above average, while Opto, Other Logic, and Programmable Logic underperformed. On an annual basis, the big winners were Discrete, Memories, Sensors, and Power Devices.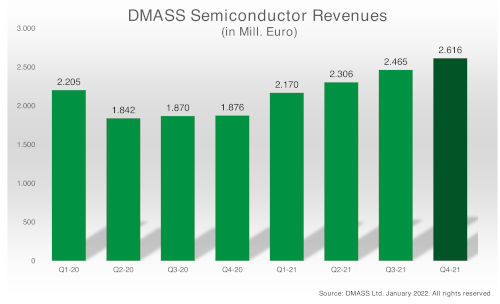
Interconnect, Passive, and Electromechanical Components:
Interconnect, passive, and electromechanical (IP&E) components closely mirrored semi-automatic components and even surpassed them on an annual basis. Annual growth of 32.1%, to €4.36 billion, represents a new record since IP&E reporting began. In the fourth quarter, IP&E grew by 39.5% to €1.13 billion. Regional growth was fairly evenly distributed, except in the case of Russia, which lagged behind. Regarding products, passives remained the largest group, increasing by 40.6% to €534 million, closely followed by electromechanical products (including connectors), which grew by 38.7% to €525 million. Power supplies (including batteries), the smallest group, remained stable with 36.9% growth and a turnover of €68 million. On an annual basis, both passives and electromechanical products showed balanced growth.
Chairman Hermann Reiter: "It's great to see our market performing so well; we have exceeded our recent expectations to some extent. It was interesting to see IP&E decline sequentially compared to the third quarter, while Semis remained strong through the end of the year. We expect 2022 to be another strong year and anticipate that the supply chain issues, such as those recently reported from China with production stoppages due to COVID-19 infections, will soon dissipate. As previously stated, the biggest risks remain the geopolitical crises between the major powers, and we hope, for the benefit of our shared business, that these conflicting interests will be resolved shortly."







