Most people still believe that flexible and adaptable electronics (SCE) are academic curiosities without a specific market. This belief seems to be based on the occasional proof-of-concept studies published, relying on the results of those rare devices that actually work. Even when companies showcase prototypes, it's easy to dismiss them as mere marketing exercises designed to make their inventors appear as R&D leaders.
However, there's much more to the SCE industry than meets the eye. At IDTechEx (the market research firm we rely on), we've been investigating this technological frontier for several years. In this article, we'll outline how many of the simpler, less glamorous aspects of SCE have already been commercialized or are on the verge of commercialization. And we'll discuss two major trends underpinning interest in SCE: (1) wearables that are truly wearable and (2) structural electronic components. Furthermore, we'll argue that viewing SCE as a single entity is entirely misleading. SCE is an umbrella term encompassing many different technologies and applications. It is appropriate to view SCE as a collection of disparate niche applications and solutions.
Wearable technology is truly becoming wearable.
Interest in wearable technology increased exponentially starting in late 2013. This was accompanied by the emergence of several new product categories that helped define new wearable technology versus old wearable technology (pocket and wristwatches, dating back centuries). These new categories include connected smartwatches, smart glasses, virtual and augmented reality glasses, and more.
Each of these categories is very different in terms of underlying technology, level of readiness, target markets, and current and future earnings potential. In fact, in a recent market forecast, our team tracked 42 different categories of wearable devices, with overall growth from a current base of around $35 billion to over $155 billion by 2027.
There is often little unification of these disparate technologies. Indeed, there is a real possibility that the different fates of these categories will render the overarching term "wearable technology" irrelevant in the not-too-distant future.
Despite this pending divergence, a common trend across almost all devices is a shift in form factor. If you analyze the current product landscape, you'll soon discover that it's simply old, rigid components assembled into a new "box" that can be worn somewhere on the body. Almost all of these components are borrowed from existing industries such as consumer electronics, medical, or automotive. There is relatively little hardware innovation to create truly wearable devices.
This is changing. As shown in Fig. 1, companies, large and small, are beginning to make wearable devices truly wearable. Often, these are early-stage exploratory products that have been developed to test the waters and are not yet mature, tested, and finished.
 Fig. 1: Wearable devices are beginning to move from rigid components in boxes to truly wearable devices. Until now, almost this entire market has featured existing sensors borrowed from other industries. However, we are now seeing new sensors made with wearability in mind.
Flexible Electronics for Wearable Technology:
Working to create truly wearable devices encompasses all the required system components. Advances are being made in stretchable and/or adaptable batteries, transistors/memories, displays, sensors, PCBs, and interconnects (flexible connections). However, most SCE components are still in a very early stage of technological readiness. Here, therefore, we focus on stretchable interconnects and sensors as two examples of SCE that are already commercially available or on the verge of commercialization.
Interconnects may seem like simple elements, but they are crucial for enabling truly wearable textile-based applications. Currently, there are several approaches to creating textile-based interconnects, including fine metal yarn and metal-coated fiber/yarn. Stretchable conductive inks are also emerging as a serious contender for this role. This is because conductive ink technology is highly adaptable, allowing for the development of customized products to meet different price and performance requirements (conductivity, stretchability, etc.). This is critical at this exploratory stage of the market when customer requirements are not fully known and can be very divergent.
Inks have an additional advantage as they are a post-production step that can be universally applied once a textile material is manufactured using existing, unmodified processes. In fact, ink technology has the potential to leverage existing infrastructure and know-how for screen-printed graphics on textiles.
As shown in Figure 2, there are already many prototypes of electronic textiles (e-textiles) and products using flexible and/or elastic conductive inks. These examples range from heart rate monitors for humans and animals (e.g., horses), pressure sensors in footwear, interconnects, and more. Overall, our statistics, shown in Figure 2, demonstrate that interest in stretchable inks is on the rise. The number of ink-based e-textile products/projects has increased significantly year-over-year.
 Fig. 2: On the left are the prototypes and products of ink-based e-textiles. (Information in parentheses indicates where/when IDTechEx analysts took the photos.) On the right are statistics showing that the popularity of ink-based solutions is increasing in electronic textiles. Source: IDTechEx.
Despite this interest, stretchable inks are not yet a finished product. There is significant room for continuous improvement and customization. In the current approach, the printed layer is sandwiched between a plastic substrate and an encapsulation layer, and then laminated onto the textile. This is not an elegant solution, as it requires two additional layers. The substrate is essentially used to create a common surface in an industry where numerous textiles exist, each offering very different surface characteristics. Common encapsulation materials are also not yet perfect, as they are not very breathable or can even be uncomfortable. The performance of stretchable inks can also be further improved, although the latest generation is better at suppressing resistivity changes with elongation and at withstanding washing conditions, compared to previous versions. All of this suggests an opportunity for material innovations and improved formulations to enable more stretchable inks that can be applied directly onto various textiles with strong adhesion.
So far, this trend has been driven by material/ink suppliers, and not all companies are experiencing commercial success. In fact, we are still in the early stages, and the value chain for e-textiles is still forming, with the active participation of traditional textile manufacturers, large contract manufacturers, and major brand owners.
Many examples of stretchable textiles (SCE) sensors are commercialized or nearing commercialization. For example, piezoresistive sensors are already in commercial use for measuring pressure distribution over uneven topographies. One use case involves measuring the topography of a patient's teeth. The patient bites down on the piezoresistive sensor, and in doing so, changes the sensor's thickness, and therefore its resistivity, in various places, allowing for a reading. In such applications, the degree of stretch is often low, while excellent surface adaptability is essential.
Many other types of stretchable sensors are also under development. One example involves stretchable strain sensors that measure large displacements (>100 percent), far beyond the capabilities of standard strain gauges. The device architecture can be relatively simple; for example, a dielectric polymer can be sandwiched between two printed electrodes to create a capacitive strain sensor. These sensors are being aggressively marketed by several vendors worldwide. The target application space is potentially very broad, encompassing e-textiles, robotics, industrial machinery, and more.
While there may appear to be a sudden surge of commercial interest and progress in SCE, these technologies don't become wonders overnight. For example, consider simple dielectric-based stretchable strain sensors. Working examples have been developed, but companies have been trying to commercialize these for over 13 years. During this time, the intellectual property and commercialization rights for this technology have changed hands at least three times, and numerous potential markets have been tested, creating a wealth of commercial experience.
Structural electronics is a possible future for electronic devices.
Structural electronics represents a megatrend that will transform traditional electronic components into truly invisible electronics that are part of the structure itself. This is a major long-term innovation that will lead to a fundamental shift in the electronics industry, including its value chain, materials, and components (Figure 3). Stretchable and adaptable electronics are shaping this megatrend. In fact, they are enabling it. Fig. 3: Structural electronics represents a trend that will make electronic functionality a part of the structure itself.
In one manifestation of structural electronics (SCE), electrodes/antennas are deposited onto the surface of 3D-shaped objects, eliminating the need for a separate printed circuit board. Here, as with piezoresistive sensors, stretchability is important in the form of a prepared 3D surface conformability rather than elasticity or high-voltage capabilities. In another manifestation, in-mold electronics (IME) is helping to structurally embed electronic functionality into three-dimensional objects manufactured using high-performance processes such as thermoforming.
In IME, electronic materials, along with graphic inks, are deposited (printed or coated) onto a flat sheet before being thermoformed into a three-dimensional shape. This causes the materials to undergo a large, one-time stretching event. If standard materials are used, this stretching will cause cracking and layer failure. Therefore, the materials used must be specially manufactured or formulated to be compatible with IME.
This presents an opportunity for material suppliers. The first material to address this need has been conductive ink, partly due to its technological adaptability in terms of custom formulations. This flexibility has helped it become IME-compatible. In fact, as with the development of commercial stretchable conductive inks, IME-compatible material is undergoing a unique stretch event. There were only two or three suppliers two years ago or so, but now many ink suppliers have demonstrated the capability or commercially launched their products, often with aggressive pricing strategies.
The menu of materials is not limited, of course, to conductive inks. Another important component becoming IME-compatible is transparent conductive films (TCFs), which form the basis of capacitive touch sensing technology. These stretchable TCF technologies, including those based on carbon nanotubes (or nanobuds), silver nanowires, and PEDOTs, can enable 3D-shaped touch surfaces created through molding processes.
As shown in Fig. 4, there are already numerous IME prototypes intended for high-volume household appliances, white goods, and automotive applications. Many of these prototypes are in the final qualification stage. Interestingly, IME had a false start in that an IME overhead console had been adopted in a car before a malfunction (attributed to the simplification of the process from prototyping to mass production) led to a product recall. This cautionary tale further underscores the fact that SCE doesn't appear overnight and has, in fact, been in development for years. Note that despite that recall, the commitment has remained strong, and we expect commercial product launches soon.
 Fig. 4: There are many examples of IME prototypes intended for high-quality household appliance applications, such as washing machine machine-to-machine interfaces, as well as automotive applications, such as overload or heating control consoles. The box on the right contains examples of various thermoformed transparent conductive films.
Sources: Clockwise from top left: Fujifilm (IDTechEx Show! USA 2016), Negase (Nepcon Japan 2017), Heraeus (IDTechEx Show! USA 2016), Aga (FineTech 2014), Canatu. (Information in parentheses indicates where/when IDTechEx analysts took the photo.).
A Slow and Cost-Effective Path to Innovation:
There will be much more innovation in SCE in the coming years, because all electronic components, to varying degrees, are becoming flexible and adjustable. As described above, most are still far from commercialization. This is partly due to technological immaturity, but also because SCE components are often very different from their rigid counterparts in terms of performance and application. Consequently, they cannot simply be considered a next-generation replacement for existing components/materials.
In fact, SCE components must find and create new markets and new product categories. This requires extensive and time-consuming exploration of many market niches. We currently see that several SCE components are precisely in this phase: the market is experiencing many divergent application ideas. This phase will inevitably end as the affected products are found, causing the industry to consolidate around them. This period of convergence will continue until competition erodes margins, forcing players to seek new markets and unleashing the next phase of divergence.
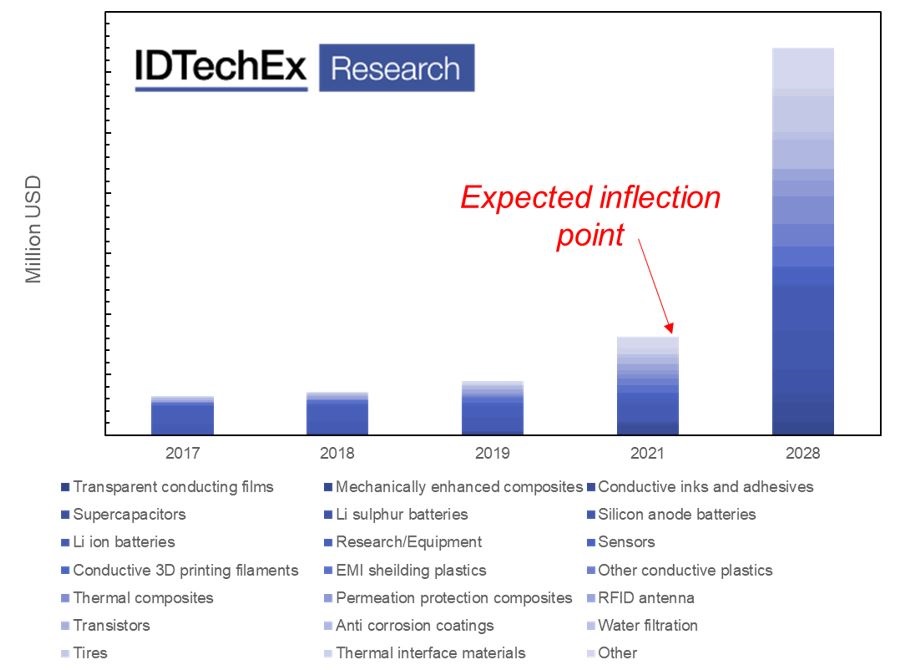
The high level of diversity, however, both in terms of technologies and target applications, will ultimately offer a significant opportunity to the stretchable and conformal electronics (SCE) market. While not every application will be successful, it would be unreasonable to assume that all applications will fail. In our forecast, we see a $600 million market for SCE by 2027. For more information, please see our report, Stretchable and Conformal Electronics 2017-2027, available at www.idtechex.com/stretchable
______