Outside the laboratory and into the market,
the commercialization of graphene is progressing steadily. This progress is evident in several key trends, which we summarize and analyze below:
1. Increased industry experience: In the early days, graphene was oversold as a wonder material or magic powder that would revolutionize almost every industry overnight. Naturally, with time, realism has set in. Today, graphene sheets are increasingly seen, and rightly so, as part of the ongoing expansion of carbon additive materials.
Furthermore, the market now recognizes that there are many graphene materials and that not all are created equal. As such, users now accept that winning materials cannot be determined beforehand, as the final results are influenced by many parameters, such as graphene morphology and formulation/composition techniques and conditions.
Consequently, users have engaged in numerous parallel qualification processes to find the graphene that works for their specific circumstances. This development, which might now seem commonplace, took several years to complete and was essential to the industry's learning curve.
2. Increased availability: Graphene has several useful properties and, as a result, a diverse portfolio of applications. However, most target applications are high-volume markets. Therefore, suppliers must take the risk of investing in substantial production in the face of small and uncertain demand.
This has been unavoidable because otherwise, suppliers would never be able to move beyond the prototyping or performance phase. This process (of installation capacity) has progressed so significantly worldwide that availability is not a major concern for the industry in the medium term.
Interestingly, and now common across many industries, China has become the leading territory in terms of nominal production capacity. Its rise to the top has also made direct liquid-phase exfoliation the leading process in terms of production capacity. This is because many Chinese producers were not part of the first wave of graphene companies that relied on the rGO process available at the time.
Further progress is still needed on this front. In particular, quality control and consistency must continue to improve.
3. Increased affordability: Graphene is largely a substitute material. As such, it must compete on price and performance with established solutions. As a new, specialized material, graphene suffers from high and divergent (by orders of magnitude) prices and pricing strategies.
This has changed. Graphene board prices have fallen and are beginning to converge, currently around $75-$125/kg. There's still a range where some charge much more, as they still cater to research markets, and a few charge much less. This latter group, we believe, sells at a loss to gain market share or for startup projects. These prices will continue to fall as utilization rates increase, allowing for more effective cost amortization.
However, prices will not settle at a single point, reflecting the diversity of graphene types and giving it a unique chemical character. Furthermore, suppliers will be reluctant to reduce costs further for fear of premature commoditization, although the continuation of this trend seems inevitable.
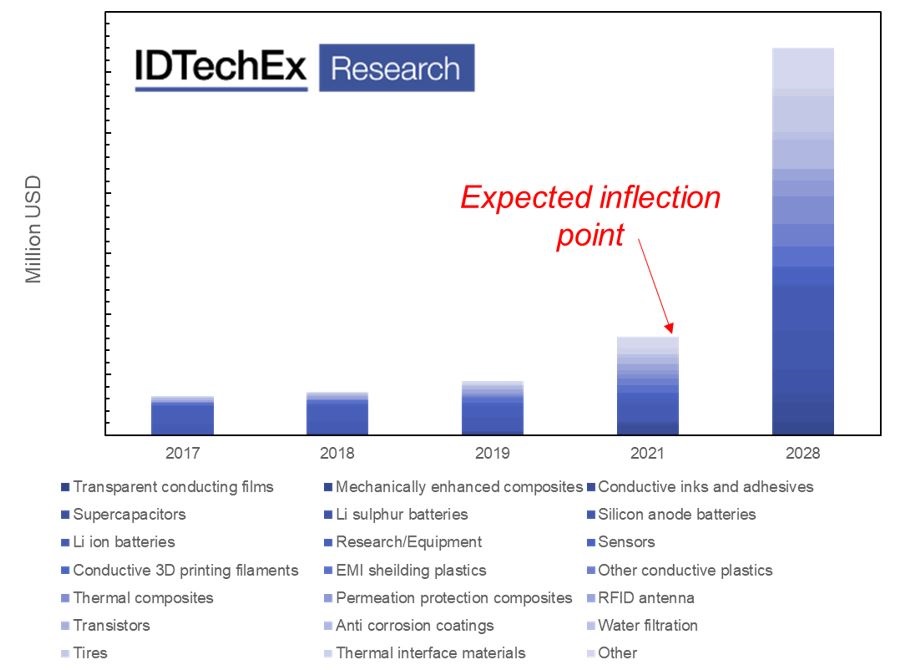
4. Increasing Sales Volume and Revenue Progress: Our data suggests that company-wide graphene revenue has been steadily increasing since 2013. This increase, which is reflected across the board, will continue at similar rates until 2021/22, at which point our model suggests a tipping point will occur, placing the market in its rapid volume growth phase.
However, this increase in revenue has not always been accompanied by an increase in profits. In fact, the opposite is often true, with losses growing in line with revenue. Indeed, the industry as a whole is still losing money despite the existence of several profitable companies.
This is not surprising, but it is likely to change soon. Experience has shown that new materials take years, if not decades, to reach the market, and the early stages of commercialization require significant investment. Graphene is no exception; therefore, this behavior is, in our opinion, a natural part of the industry's growth process.
Medium- to long-term outlook:
The graphene market has inherent strength. This is because the pipeline of applications is incredibly diverse. This means that while graphene won't succeed in every application, it also won't fail in every application. Consequently, this diversity lends resilience to the future commercial prospects of this new material.
We assess that 2021/2022 is likely to be a turning point for graphene. This is because, by that time, market benchmarks for various use cases are likely to exist, more qualification processes will have been completed, production costs will have decreased further due to increased volume demand, supply consistency will have been addressed, and so on.
A $300 million market at the materials supply level will form within the next ten years. Since graphene is still largely an additive material, this means we will find graphene, in various forms, in numerous high-volume applications in the years to come. This success, it is worth remembering, will not have happened overnight, but will be the result of nearly two decades of sustained global research and commercialization efforts.
For more information about this emerging market, see our report "Graphene, 2D Materials and Carbon Nanotubes: Markets, Technologies and Opportunities 2018-2028".
Written by Dr. Khasha Ghaffarzadeh, Director of Research, IDTechEx