

Figure 1 shows the sales ranking of the top 10 semiconductor suppliers (ICs and OSDs: optoelectronic, sensor, and discrete) for Q1 2020. It includes six suppliers based in the US, two in South Korea, and one each in Taiwan and China. The ranking includes four companies without manufacturing facilities (Broadcom, Qualcomm, Nvidia, and HiSilicon) and one "Pure-Play" foundry (TSMC).
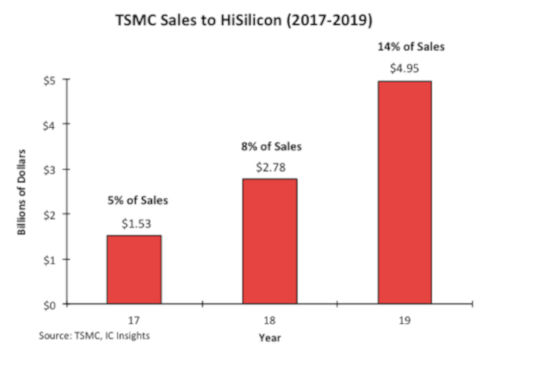
Overall, sales for the top 10 semiconductor companies increased by 16% in Q1 2020 compared to Q1 2019, more than double the overall 7% increase for the global semiconductor industry from Q1 2020 to Q1 2019. Nine of the top 10 companies had sales of at least $3 billion in Q1 2020, one more than in Q1 2019. As shown, it took nearly $2.7 billion in quarterly sales just to break into the Q1 2020 top 10 semiconductor vendors list. There were two new entrants in the top 10 rankings in Q1 2020: HiSilicon and Nvidia. These two companies replaced Infineon and Kioxia in the top 10. HiSilicon is the semiconductor design division of China-based telecom giant Huawei, and over 90% of HiSilicon's sales go to its parent company. As shown, HiSilicon, a China-based IC supplier without a manufacturing facility, climbed five places in the rankings to tenth, becoming the first China-based semiconductor supplier in the global top 10. HiSilicon's annual sales increased by 54% in Q1 2020. Nvidia also recorded a solid year-over-year sales increase of 37% in Q1 2020. The top 10 ranking includes a "Pure Play" foundry, TSMC, which recorded a strong 45% jump in revenue from Q1 2020 to Q1 2019. Much of this increase was due to a rise in sales of 7nm application processors to Apple and HiSilicon for their respective smartphones. As shown in Figure 2, HiSilicon has become an increasingly important customer for TSMC, accounting for 14% of its sales last year, up from just 5% in 2017. Interestingly, HiSilicon and Apple combined represented 37% of TSMC's total sales in 2019.
 IC Insights includes foundries in its Top 10 Semiconductor Suppliers ranking because it has always viewed the ranking as a list of leading suppliers, not a market share ranking, and recognizes that, in some cases, semiconductor sales are counted twice. Since many customers are vendors within the semiconductor industry (supplying equipment, chemicals, gases, etc.), excluding large integrated circuit manufacturers (ICMs) like foundries would leave significant gaps in the top semiconductor suppliers list. As shown in the list, foundries and non-fabrication companies are identified. In the April McClean Report Update, IC supplier market share rankings by product type were presented, and foundries were excluded from these lists. Overall, the Top 10 list shown in Figure 1 is provided as a guide to identifying which companies are leading semiconductor suppliers, whether they are IDMs, non-fabrication companies, or foundries. Many of the leading semiconductor companies have provided their sales guidance for Q2 2020, which will be presented and discussed in the May Update. Overall, Q2 2020 semiconductor market revenue expectations vary widely by company, as would be expected during the height of the current pandemic, and now span a 17 percentage point range. As part of the May Update, IC Insights will also discuss its expectations for global quarterly growth in the IC market for the remainder of this year.